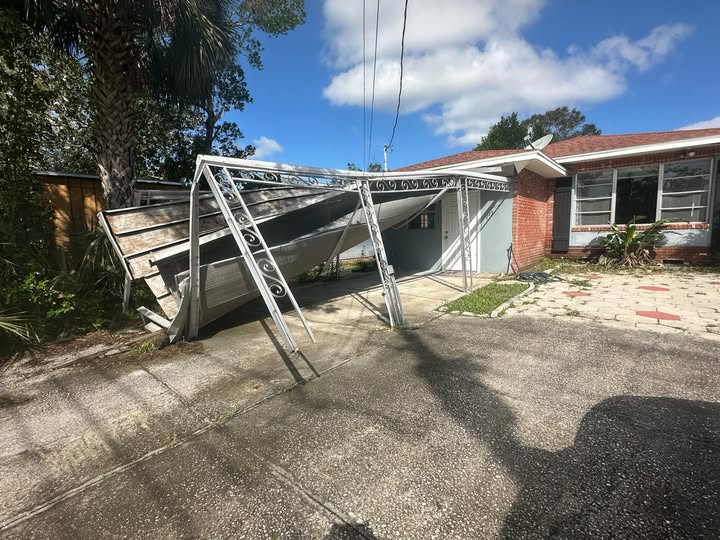
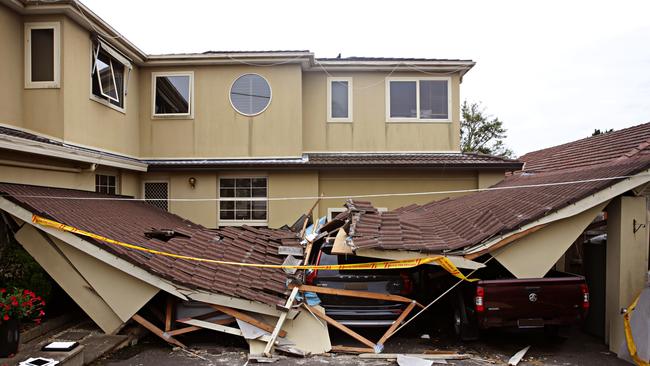
Insurers commission an independent engineering report whenever a claim's outcome genuinely depends on establishing cause, most structural damage claims fall into this category, because coverage typically hinges on whether the damage resulted from an insured event (a storm, an impact, a burst pipe) or an excluded cause (wear and tear, a pre-existing defect, poor original construction). See our piece on what is a forensic structural engineer for what that investigation actually involves.
The Kinds of Claims That Trigger a Report
- Storm and weather damage, where the question is usually whether damage is genuinely storm-related or was already present, covered in detail in storm damage or pre-existing defect: how the difference gets determined.
- Structural cracking or movement claims, particularly where subsidence or footing movement is suspected, since most policies treat gradual, non-sudden ground movement very differently to sudden damage.
- Impact damage, such as a vehicle striking a structure, covered in structural assessment after vehicle impact.
- Disputed or high-value claims, where the insurer wants independent verification before authorising a significant payout, or where the insured is disputing an initial assessment.
Why It Has to Be Independent
An engineer engaged directly by a builder or the party responsible for the damage has an inherent, if unstated, interest in the outcome. Insurers generally require a report from an engineer with no financial stake in the claim's result, prepared to the same standard of independence expected of expert evidence more broadly, the principle covered in our piece on independence under Schedule 7. This is also why registration matters, see why a registered professional engineer's report carries more weight.
What This Means for Homeowners
If you're making a claim involving structural damage, it's worth expecting an independent engineering assessment to be part of the process, and engaging one yourself early, rather than waiting for the insurer to arrange it, can help ensure the damage and its likely cause are properly documented from the outset. Our piece on structural engineer reports for insurance claims covers what that documentation actually needs to contain, and our plain-English guide on whether structural damage is covered by home insurance explains why cause matters so much to the outcome. If the insurer's assessment comes back against you, our piece on your options after a declined structural claim covers the dispute process and where a second independent opinion fits into it.